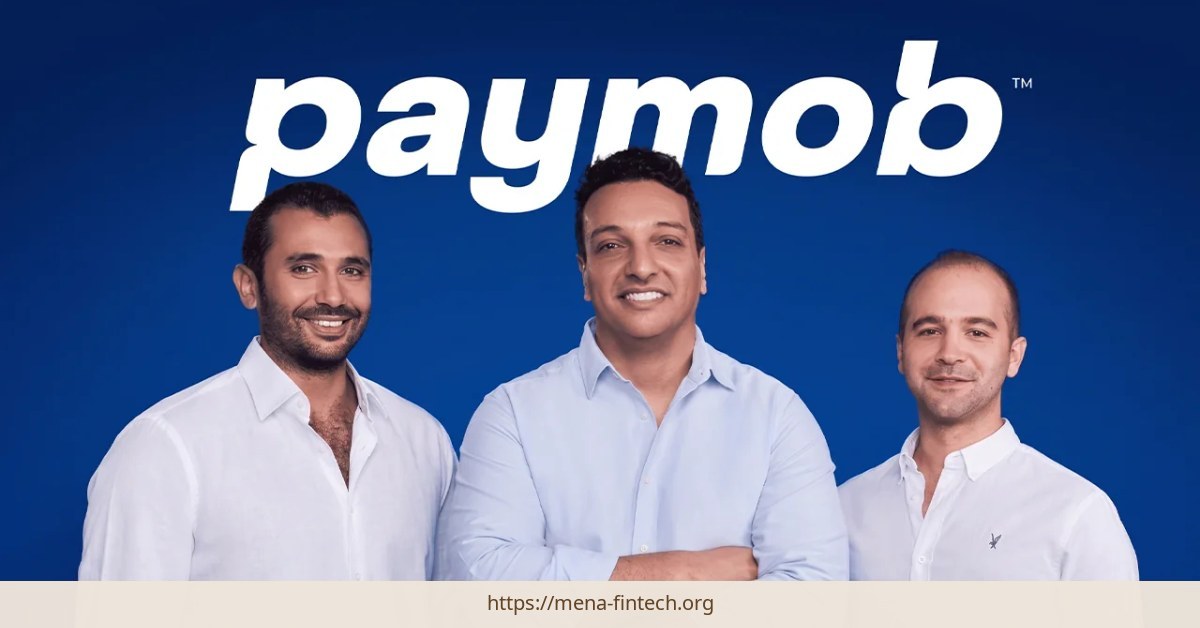
Paymob has raised $35 million in a Pre-Series C funding round, co-led by Mubadala and the European Bank for Reconstruction and Development (EBRD). The funding will be used to scale Paymob’s operations across the MENA region, enhancing digital payment infrastructure.
Significance of the Funding
The $35 million round underscores growing international interest in MENA fintech, particularly in payments infrastructure. With participation from Mubadala, EBRD, British International Investment, Global Ventures, and DPI Ventures, the investment signals confidence in Paymob’s role as a regional payments enabler. This follows a broader trend of cross-border capital flowing into MENA’s digital finance sector, where adoption of mobile payments and embedded finance solutions has accelerated.
For regional financial institutions, the development highlights the strategic value of partnerships with established payment infrastructure providers. The funding could accelerate the deployment of interoperable payment corridors, API-driven banking solutions, and real-time settlement networks across GCC and non-GCC MENA markets. These advancements align with regional digital transformation goals, including Saudi Arabia’s Vision 2030 and the UAE’s push for a cashless economy, which prioritize financial inclusion and technological innovation.
The involvement of Mubadala and EBRD, both known for their strategic investments in emerging markets, suggests a long-term commitment to strengthening MENA’s financial ecosystem. Mubadala’s focus on technology and infrastructure aligns with Paymob’s mission to modernize payment systems, while EBRD’s participation reflects its mandate to support economic development in transition economies. This partnership could catalyze further investment in fintech startups across the region, fostering a competitive landscape that drives innovation in digital services.
What Wasn’t Disclosed
The announcement did not specify timelines for expansion, projected transaction volumes, or named banking partners that would integrate Paymob’s infrastructure. It also omitted details on how the capital will be allocated across product development, market entry, and regulatory compliance initiatives.
The absence of concrete timelines raises questions about the pace of Paymob’s regional rollout. While the company has previously expanded into Egypt, Jordan, and the UAE, the new funding may enable deeper penetration into underserved markets such as Iraq, Lebanon, and Morocco. However, without clear milestones, stakeholders may find it challenging to assess the company’s growth trajectory.
Similarly, the lack of named banking partners leaves uncertainty about the scope of Paymob’s integration plans. Collaborations with local banks or international financial institutions could determine the scalability of its solutions, particularly in markets with fragmented regulatory environments. The omission of projected transaction volumes also limits the ability to gauge the potential impact on the region’s payment ecosystem.
Significance: For MENA fintech, the funding reflects the continued convergence of payment infrastructure, digital assets, and real-world asset tokenization in the region. It also points to a model in which blockchain providers seek distribution through regulated financial institutions rather than replacing banks, exchange houses, or payment companies outright.
For regional financial institutions, the practical question will be whether the joint venture can translate its corridor and tokenization plans into licensed, bank-compatible services across multiple jurisdictions. Until specific approvals, partners, and launch volumes are disclosed, the development is best treated as an infrastructure initiative to monitor rather than a completed market rollout.
Sources
- Paymob Raises $35M Pre-Series C to Expand Across MENA – menastartupdigest.com
Image: waya.media