On 20 July 2026, the UAE formally began nationwide issuance of Jaywan, its first national card scheme. A day later, Al Etihad Payments announced a partnership with Mastercard that would allow Jaywan-Mastercard co-badged credit cards to be used globally while also establishing a new Mastercard operations centre in the UAE to process domestic and international flows. Taken together, the two moves capture something important about the country’s payments strategy. The UAE wants more control over the infrastructure beneath everyday transactions, but it also wants that infrastructure to connect outward. A national payments system is useful for resilience, cost and control. A global payments hub, by contrast, depends on whether money can move through that system easily enough for international businesses to choose it as part of their normal financial architecture. That distinction sits at the centre of Shevtsova’s view of the UAE payments market.
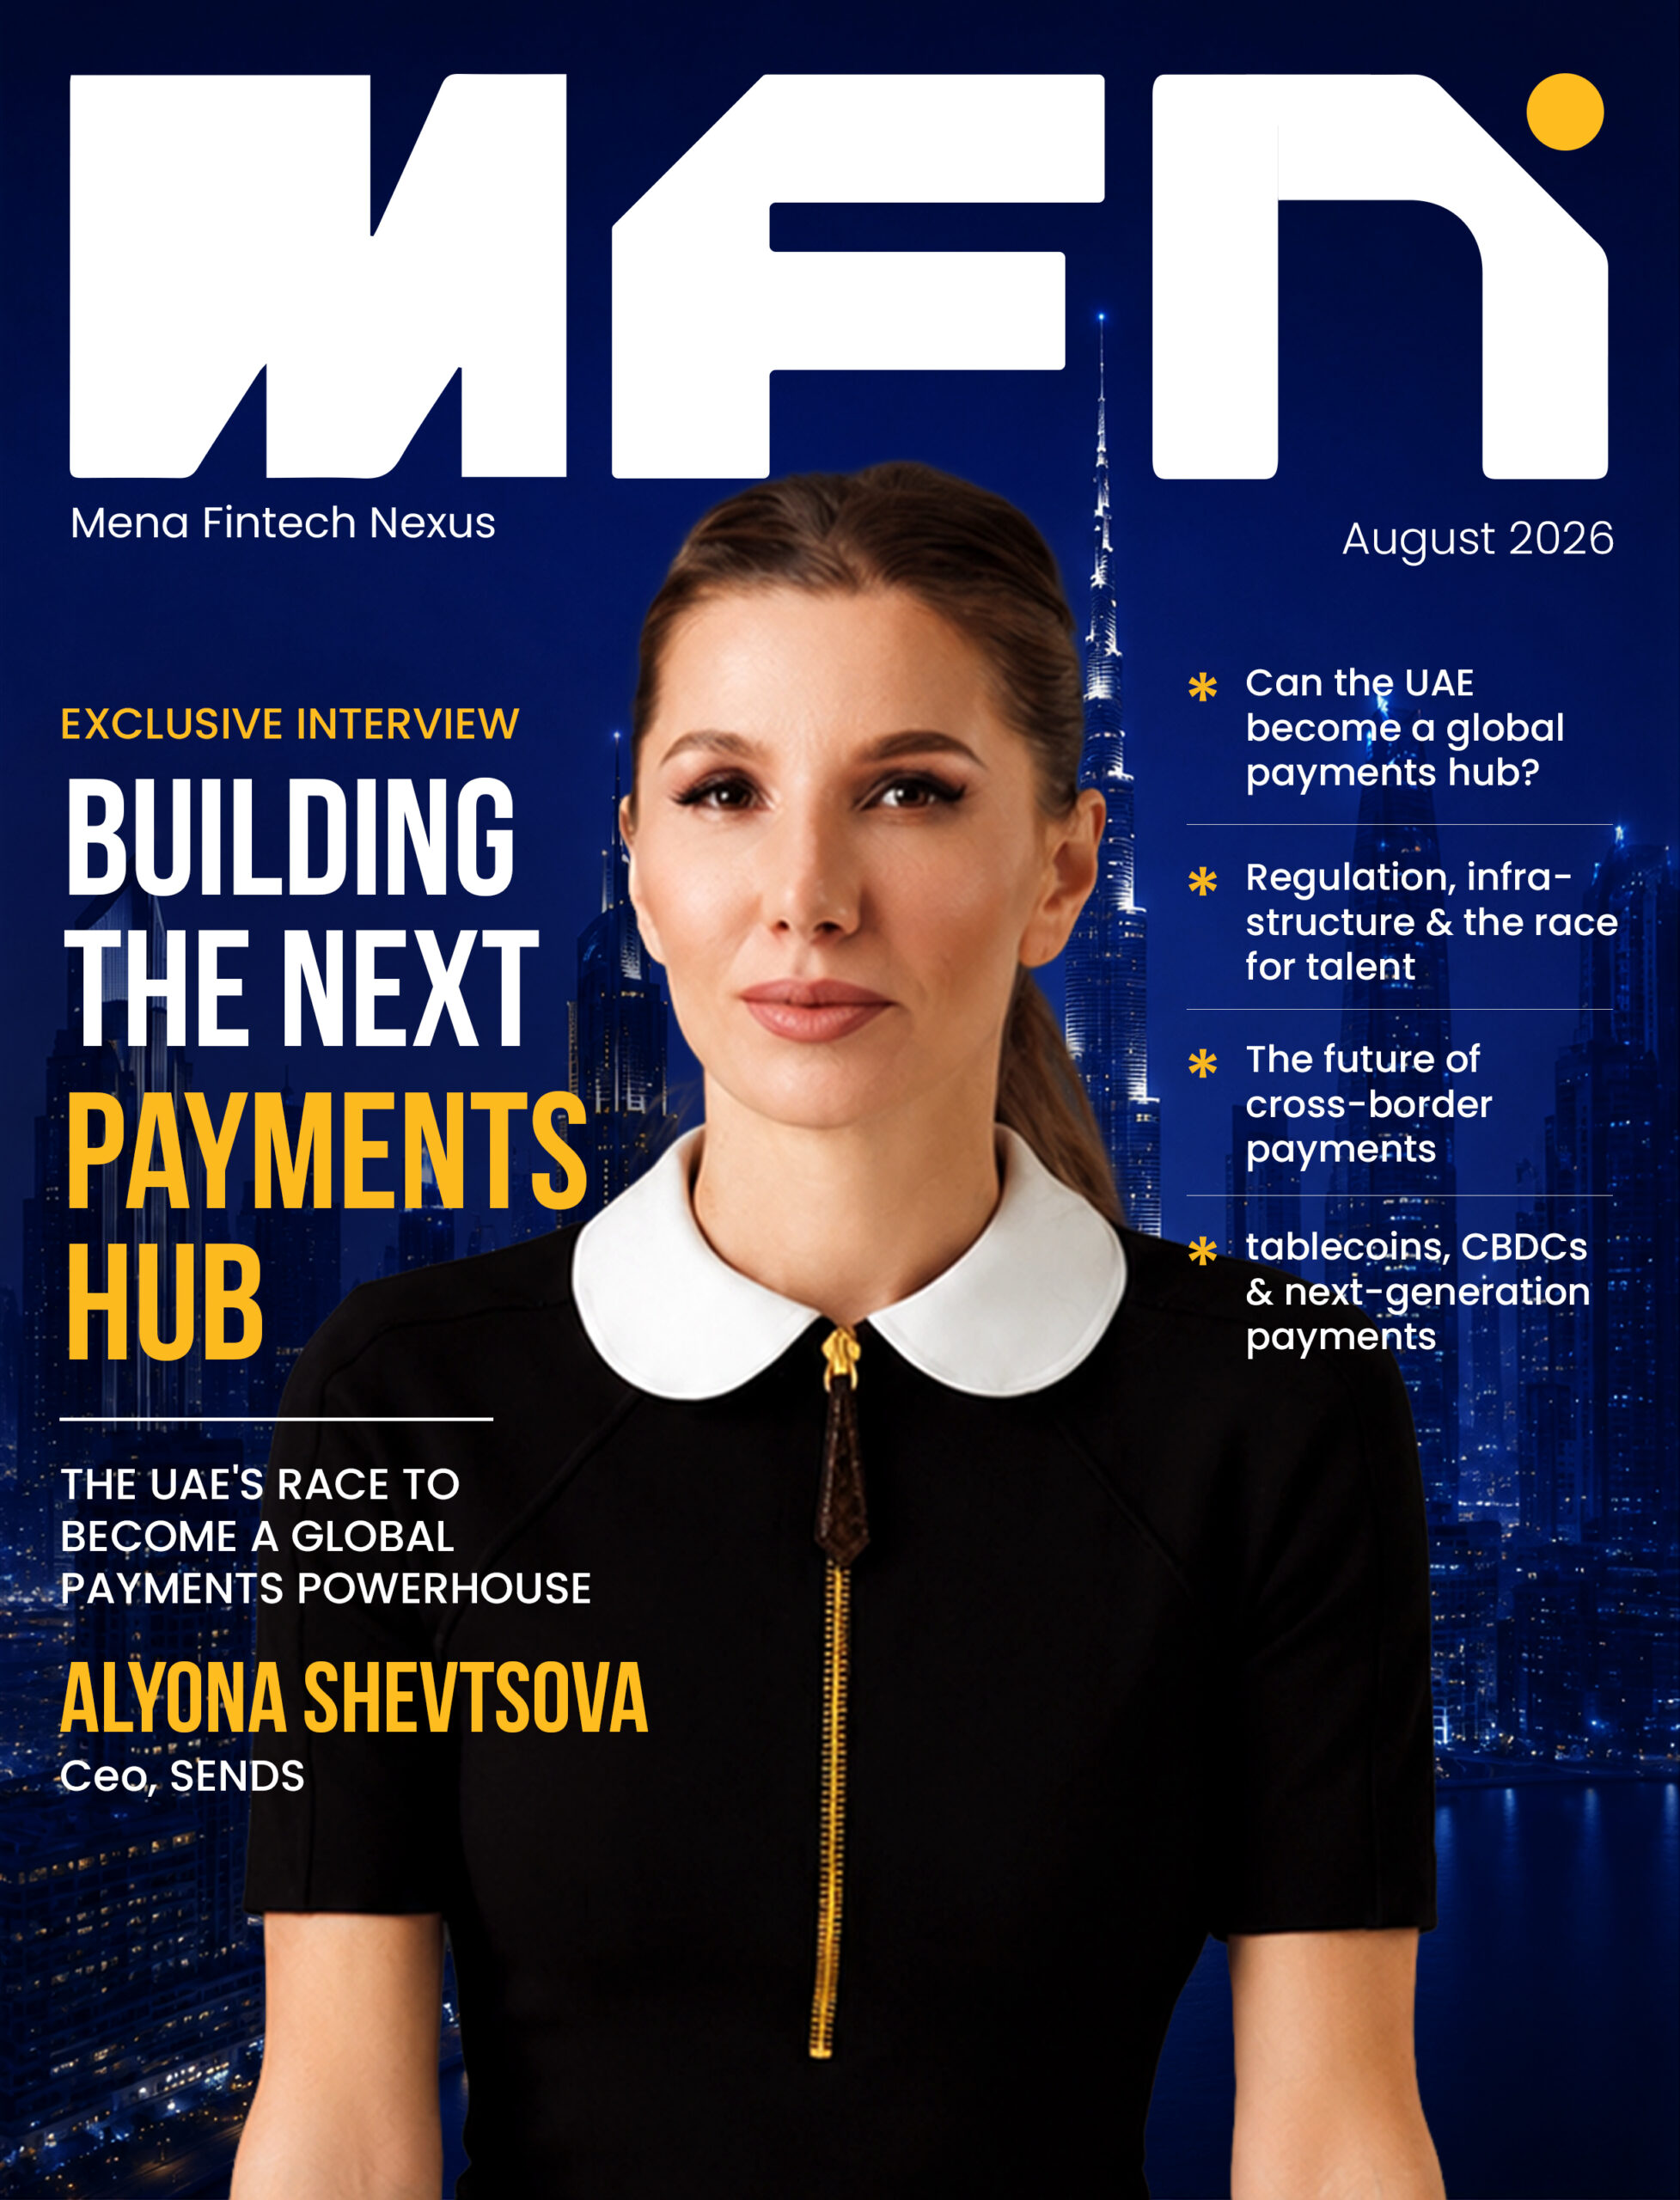
Alona Shevtsova is the Founder and Chief Executive of SENDS, an FCA-authorised electronic money institution headquartered in London, providing businesses with multi-currency accounts, cross-border payments and FX services. With more than 15 years of experience across payments and financial technology, much of her perspective on the Gulf centres on one key question: What will demonstrate that the UAE has evolved beyond being a well-connected regional gateway? Her answer is practical. By 2030, she argues, success should be measured less by the number of companies registered in the country and more by the volume and value of activity actually flowing through its financial ecosystem. International businesses should be using the UAE as a bridge between Europe, Asia and Africa; B2B settlements should become faster and more transparent; domestic payment rails should operate seamlessly across institutions and borders; and the country should develop a deeper pool of homegrown expertise in payments and compliance.
The First Test Is Execution
The UAE is hardly starting from scratch. Its regulatory architecture has expanded alongside the market, with the Central Bank, financial free zones and specialist digital-asset regimes creating different routes for companies depending on what they do. Shevtsova sees the pace of rulemaking as an attraction rather than a deterrent. In her experience, regulators in the country have been unusually open to communication and willing to engage with firms trying to understand where a product fits. “The speed is the huge advantage, but it only works if it’s paired with clarity,” she says. Multiple regimes can create friction, especially for companies deciding where to license and how one activity might fall across more than one framework. Yet she does not treat that complexity as fatal. The more important question is whether firms can see a credible path from pilot to licensed scale and whether regulators can explain what compliance looks like after launch, not only at the application stage.
The harder gap is one that cannot be solved by issuing another rulebook. Shevtsova says the UAE is “winning on vision and opportunity” while still catching up on the depth of specialist talent found in older centres such as London. That comparison matters because mature payments ecosystems are built around accumulated operating experience: people who have launched products in several markets, run large compliance teams, managed sanctions exposure, built risk systems and lived through the expensive mistakes that accompany scale. The UAE can import some of that experience, and its tax environment, quality of life and concentration of investment make relocation easier to sell than in many emerging fintech centres. Shevtsova made the move herself, relocating to the UAE with her family of five children. Asked what would bring other experienced operators, she named three things: clarity on long-term career paths rather than build-and-leave stints, sustained investment in certification and exposure to multiple jurisdictions, and a culture that treats risk and compliance as strategic functions rather than cost centres. Shevtsova, who has sometimes been the only woman in the room, argues that the region’s leadership pipeline has to widen beyond the functions where women are already visible. Representation in communications and customer experience is not the test. Engineering, risk, compliance, product and investment decisions are. Still, a hub becomes more resilient when that expertise is reproduced locally. The next generation of compliance leaders, payments architects and product specialists needs to be developed inside the ecosystem rather than continuously recruited into it.
The Flows Already Exist
Geography gives the UAE an advantage that is difficult to manufacture. It sits between some of the world’s busiest trade and remittance corridors, with South Asia particularly important to the story. For Shevtsova, that makes the region a natural testing ground for cross-border finance. The volumes already exist, as do the consumers and businesses that feel the consequences when a transfer is slow, opaque or expensive. This is a different starting point from building fintech infrastructure first and waiting for use cases to appear later. The UAE has people sending money home, companies paying overseas suppliers, regional headquarters moving funds between markets and businesses trading across currencies every day. A payments hub can be built around those real flows if the infrastructure makes them materially easier to manage. Remittances show why that matters. The World Bank’s Remittance Prices Worldwide database recorded the global average cost of sending remittances at 6.36% of the amount transferred in Q3 2025, the most recent quarter published. Costs to South Asia averaged 5.30% in the same release. The global figure hides large differences across corridors, but it is still a reminder that a transaction that feels instantaneous on a phone can carry costs created by foreign exchange spreads, intermediaries, compliance processes and the structure of the route itself. Shevtsova sees a specific opening for the UAE here. With instant payments, digital identity and a regulator pushing financial infrastructure forward, she argues that the country could become a “benchmark corridor for how to do remittance right.” The test would not be another consumer app. It would be transparent pricing, faster settlement and risk systems that can distinguish genuinely suspicious activity from ordinary cross-border behaviour without treating every transaction as a problem.
The bigger commercial prize may sit in B2B payments, where the payment itself is only one part of the work.
“B2B is where the real complexity and the real value sits,”
Shevtsova says, pointing to purchase orders, invoices, multiple approvers, compliance checks and reconciliation. The Gulf already has large trade, logistics, construction and technology platforms, yet payments can still sit outside the workflow rather than inside it. That creates room for a different kind of infrastructure: instant settlement tied to invoicing, structured payment data that simplifies reconciliation, clearer audit trails and open-finance connections that reduce the time between an approved commercial decision and the movement of funds. Shevtsova argues that the UAE could use those tools to compress processes that take days or weeks into hours or seconds. For a trading centre that already links Europe, Asia and Africa, that would make the payments layer reinforce the commercial role the country already plays rather than operate as a separate industry around it.
Shevtsova sees the same logic extending to wallets, which she argues are becoming the interface through which people and businesses manage their financial lives rather than simply a way to store money or complete a payment. Fragmentation shows up most sharply on the business side: a company operating across the UAE, Saudi Arabia and neighbouring markets can need a different banking relationship, payment method and settlement arrangement in each one. Her conclusion is that the Gulf does not need a single dominant wallet. It needs better-connected financial infrastructure, so that wallets, banks and fintechs interoperate cleanly enough that the fragmentation stops being a barrier.
Sovereignty Without Isolation
Domestic infrastructure is often described as a sovereignty project, and Jaywan makes that visible. The UAE now has a nationally owned card scheme whose domestic transactions can be processed through local infrastructure. Yet the most revealing part of the strategy may be the effort to make that domestic scheme useful outside the country as well. The Mastercard partnership announced in July includes globally accepted co-badged cards and a new processing node in the UAE tied into Mastercard’s wider network. That design points toward a model in which domestic control and international connectivity are meant to reinforce each other rather than compete. Shevtsova takes a similar view of both Jaywan and Aani, the UAE’s instant-payments infrastructure. National rails, in her view, are a strength if they are built with interoperability in mind. She points to Europe’s experience with SEPA and the UK’s Faster Payments system as examples of infrastructure that is national or regional in origin but becomes more valuable when it is designed to connect. That principle is easy to state and difficult to execute. Banks, electronic money institutions, card networks, wallets and cross-border providers do not all use the same systems, data standards or compliance processes. The real measure of a domestic rail is not how elegantly it works inside one controlled environment, but how much complexity it removes when a transaction moves beyond that environment.
This also changes how newer technologies should be judged. Asked which technologies will matter most over five years, she put AI first, on the grounds that it improves infrastructure already in use: detecting unusual behaviour, routing payments more intelligently, managing liquidity and reducing manual compliance work. On tokenisation she is interested in specific applications rather than headlines, naming tokenised deposits, regulated payment tokens and digital identity. Shevtsova is cautious about treating blockchain as a solution by itself. A distributed ledger does not automatically make a payment faster, safer or more useful; the relevant question is what problem it solves and how it connects to existing financial infrastructure. Her view of stablecoins follows the same logic. Issuing a token is the easy part. Connecting it to bank accounts, sanctions screening, customer protection, liability rules and payment networks is where institutional confidence is won or lost. She sees stablecoins as an “additional regulated rail” rather than a substitute for banks or established payment institutions. “The future will probably be multi-rail,” she says. Customers are unlikely to care which underlying mechanism completes the transfer if the money arrives quickly, safely and predictably. The Digital Dirham fits into that wider architecture. As of the Central Bank’s 2025 annual report, the digital currency had progressed through implementation milestones, with a wallet developed for retail and wholesale use and the first live government transaction completed in 2025. Shevtsova’s emphasis is less on the symbolism of a central bank digital currency and more on what it can actually do. Cross-border settlement, traceability and efficient government or business disbursement would make it useful infrastructure. Adoption still turns on interoperability, acceptance, conversion and trust. A CBDC, a stablecoin, an instant-payment rail and a card network can all coexist. The hub advantage comes from making those systems work together without forcing the customer to understand the plumbing beneath the transaction.
Scale Exposes the Gaps
The faster a payments ecosystem grows, the less forgiving its weaknesses become. Shevtsova is careful not to equate more transactions with more maturity. Asked whether risk and compliance infrastructure is developing at the same pace as payments innovation, she gives a qualified answer: “Progress is strong, but the two are not always moving at exactly the same speed.” New payment products can be launched in months. Building experienced compliance teams, a strong risk culture and systems that work across jurisdictions takes longer. The challenge becomes sharper as the UAE positions itself for international flows because cross-border payments carry fragmented data, different regulatory expectations and more opportunities for fraud to move between institutions before anyone sees the full pattern. The nature of that fraud is changing as well. Shevtsova points to synthetic identities, AI-generated fraud, account takeovers and transactions that travel through several jurisdictions. The old response was to add more rules and more investigators. At scale, that quickly becomes expensive and noisy. SENDS, she says, uses AI to enrich alerts and identify patterns across transactions, customers and corridors. The purpose is not to remove human judgment from compliance decisions. It is to give investigators better information sooner, so that scarce expertise is spent on meaningful risk rather than sorting through repetitive alerts. The broader lesson for the UAE is that a modern payments hub cannot bolt compliance onto the end of a transaction. Risk intelligence has to develop alongside the rails themselves.
That requirement also changes how international firms should think about entering the market. Shevtsova’s advice is strikingly unglamorous: “I will start with the customer and the activity,” not the office, logo or brand book. A company needs to define whether it is providing acquiring, remittance, account services, digital assets, payment technology or another regulated function before it chooses a licensing route. That is an important marker of how the UAE ecosystem is maturing. Early-stage financial centres often compete primarily on ease of setup and headline incentives. More developed ones force companies to answer harder operating questions about what they are actually doing, where the risk sits and which regulator should supervise it. If international firms can navigate that process with enough clarity to build serious regional operations, the presence of multiple frameworks becomes manageable rather than paralysing.
The regional context matters too. Saudi Arabia is investing heavily in its own fintech and payments ecosystem, but Shevtsova does not see the Gulf as a winner-takes-all market. She argues that the region can support more than one important payments centre and may be stronger because of it. The more useful competitive question is whether the UAE and Saudi Arabia can make their standards and regulatory approaches interoperable enough for companies to operate across the Gulf without rebuilding the same infrastructure market by market. In her words, greater interoperability would make the whole region more attractive to global firms and capital. A payments hub does not become global by making every transaction terminate at its own border. It becomes useful when it reduces the cost of reaching the next one. By 2030, that leaves the UAE with a more demanding scorecard than the number of fintech licences issued or corporate logos added to a financial district. Shevtsova wants to see international companies using the country to connect regions, more transparent B2B settlement, interoperable instant-payment rails, digital identity, stronger cross-border data standards and a deeper pool of locally developed payments and compliance talent. She also argues that the UAE should begin exporting financial technology rather than mostly importing platforms and expertise from established centres. Homegrown companies serving customers across several markets would be one sign. Another would be UAE-built infrastructure appearing inside international payment journeys even when the end customer has little reason to know where the transaction is being processed.
That is why Shevtsova reduces the next phase to a deceptively simple choice: whether the UAE builds “for interoperability or for isolated national champions.” The country has already shown that it can launch national infrastructure, attract international networks and move quickly on regulation. The harder work is connecting those achievements. Domestic rails need to talk to banks, EMIs, cards and international payment systems. Risk information needs to move fast enough to match the transactions it is monitoring. Talent needs to deepen as the technical complexity rises. New forms of money need to integrate with old ones. None of those tasks produces the same headline as launching a new scheme, but they determine whether the scheme becomes part of something larger.
The Next Phase Is Connection
The UAE’s payments ambition is entering the stage where execution matters more than announcement. Jaywan, Aani, the Digital Dirham, new licensing regimes and the arrival of global payment companies give the country many of the components associated with a leading financial centre. They do not, on their own, settle the question. The stronger test is whether companies begin routing meaningful international activity through the UAE because doing so makes commercial sense: settlement is faster, compliance is clearer, infrastructure connects cleanly, risk can be managed and the talent exists to keep the system running as volumes grow. Shevtsova’s 2030 benchmark is useful because it measures activity rather than presence. A genuine payments hub will be visible in the movement of money through the ecosystem and in the technology the UAE exports beyond it. By that measure, the country has already built much of the machinery. What comes next is making the pieces work as one system. Shevtsova is committing her own firm to that vision. SENDS intends to pursue regulatory authorisation in the UAE, with the aim of becoming part of the country’s growing ecosystem and contributing to its connection with international markets.
Interested in knowing more? Reach out to us at marketing@mena-fintech.org
Become a part of the MENA Fintech Association: