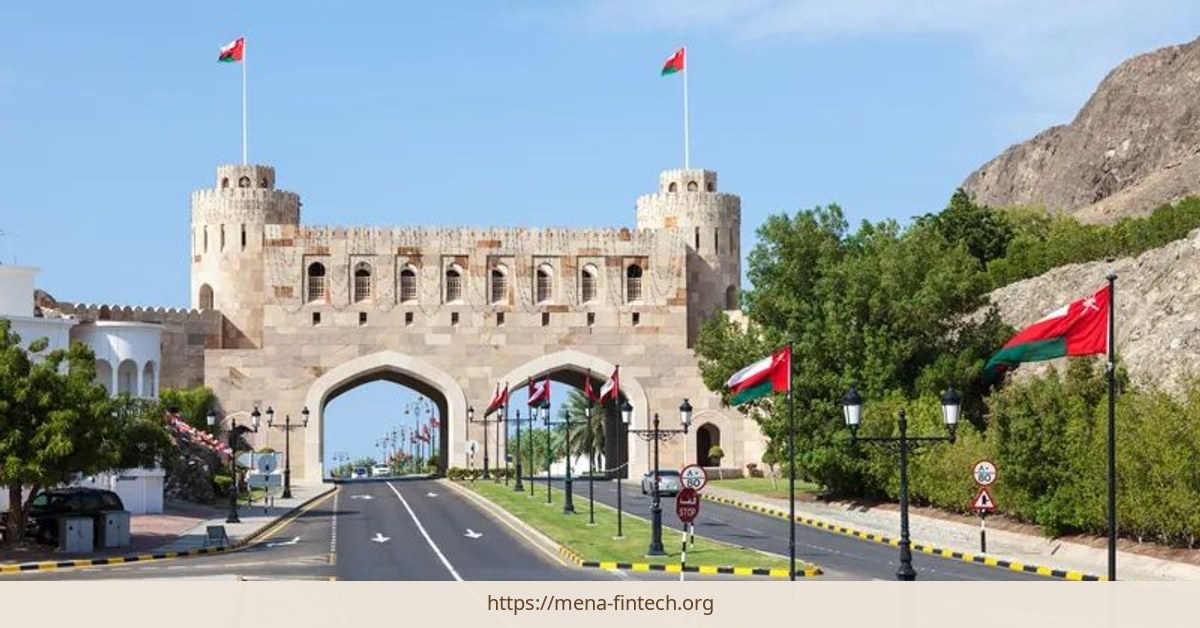
Oman’s fintech sector has grown to 42 companies, up from 26 a year earlier, reflecting a significant shift in the digital payments landscape.
Regulatory Developments
The Central Bank of Oman approved 16 new fintech licenses in 2025, contributing to the sector’s expansion. There are currently 52 additional fintech applications under review by the regulator. These developments align with the Central Bank’s efforts to enhance digital payment infrastructure and support innovation in financial services. The licensing process, which includes rigorous compliance checks and alignment with national financial strategies, underscores the regulator’s commitment to fostering a competitive yet secure fintech environment. This proactive approach is part of Oman’s broader economic diversification goals, aiming to reduce reliance on oil revenues and position the country as a regional hub for digital finance.
Market Implications
The rise of fintech companies may challenge traditional banks in Oman. Increased competition could lead to improved services and lower costs for consumers. As the sector grows, traditional financial institutions may need to adapt their strategies to remain competitive in a rapidly evolving market. For instance, banks are increasingly investing in digital transformation initiatives, such as mobile banking platforms and AI-driven customer service tools, to retain their market share. This dynamic interplay between fintechs and traditional banks is expected to drive innovation across the financial ecosystem, benefiting end-users through enhanced accessibility and personalized financial solutions.
Significance
For the MENA fintech landscape, Oman’s growth reflects a regional trend toward digital financial services. This development could influence investment and innovation across the region. The expansion of Oman’s fintech sector signals a shift in consumer behavior, with a growing preference for digital solutions over traditional banking methods. As a result, investors and entrepreneurs in the MENA region may look to Oman as a model for regulatory frameworks that balance innovation with financial stability. For market participants, the practical question is how traditional banks and fintechs will collaborate or compete to meet consumer demand for faster, more accessible financial solutions. Potential partnerships, such as co-branded digital wallets or shared infrastructure platforms, could emerge as a way to leverage the strengths of both sectors.
What Wasn’t Disclosed
The announcement did not provide corroboration for the stated growth figures or details on the 52 pending applications. The Central Bank of Oman has not publicly confirmed the exact timeline for reviewing these applications or the criteria for approval. This lack of transparency may raise questions about the regulatory process’s efficiency and the potential for delays in scaling the fintech sector. Additionally, the absence of data on the performance metrics of existing fintech companies—such as user adoption rates or revenue growth—limits the ability to assess the sector’s long-term viability and impact.
Sources
- Oman’s Fintech Sector Grows to 42 Companies as Digital Market Expands – menastartupdigest.com
Image: jawlah.co